
Bank statements
3 to 6 months of business bank statements
Business Capital Advisors
Flexible revolving capital you draw on as needed.
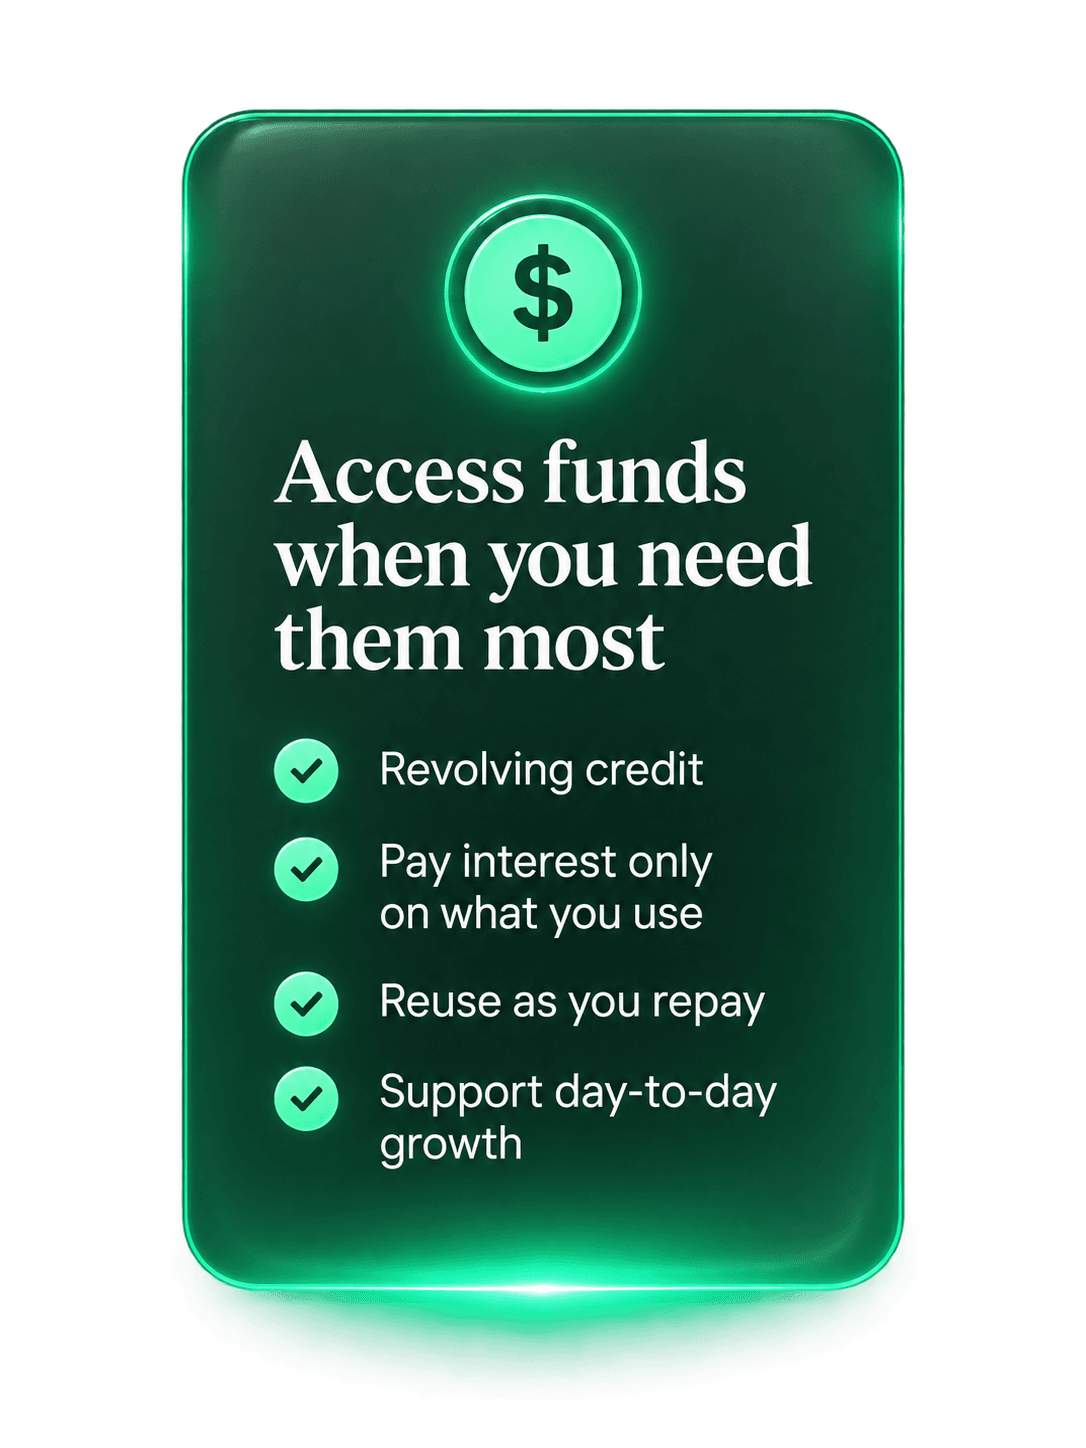
Borrow, repay, and borrow again, interest only on what you use. Built for uneven cash flow and recurring short-term needs.
Is this the right solution?
Keep the team paid while customer cash catches up.
Popular for: Professional services · Contractors · Seasonal businesses
Checking options won't affect your credit score.
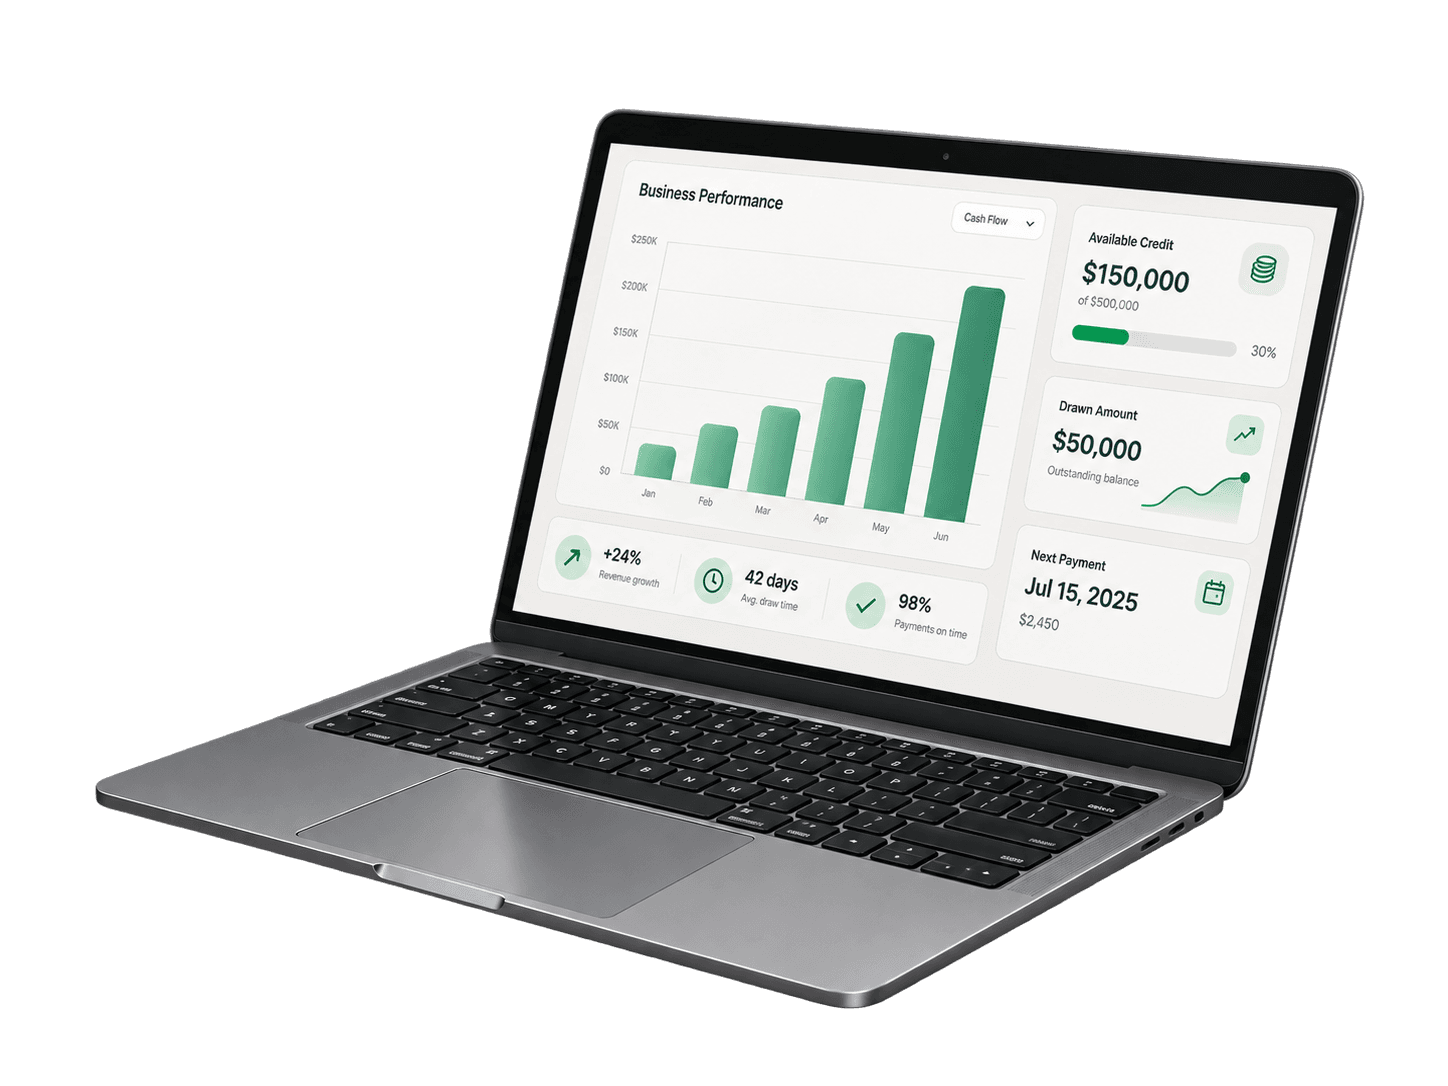
*Illustrative interest-only estimate on the selected outstanding balance. Actual approval, rate, fees, collateral, minimum payments, draw rules, and term depend on the applicant and funding partner.
Common ways businesses use a line of credit
Product definition
A business line of credit is a reusable credit facility: the business draws what it needs, repays the balance, and can draw again while the line remains open. That structure fits recurring working-capital gaps better than a one-time project with a fixed budget.
How a business line of credit works
Tell us about the business and the recurring capital need.
We review revenue, cash flow, and operating history.
Compare approved limits, rates, fees, and draw rules.
Draw what the business needs, when it needs it.
Repay the balance and restore available credit.
What you'll need
3 to 6 months of business bank statements
Driver's license and voided check
Bank lines: business tax returns and financial statements
We keep your information secure and private.
Common questions
Limits, draw rules, fees, and pricing vary by partner and business profile. Start with the questions owners ask first.
A term loan is a single lump sum repaid on a fixed schedule. A line is revolving: draw what you need, repay, and draw again, paying interest only on what is outstanding. Lines fit recurring gaps; term loans fit one defined expense.
Usually nothing, some lines carry a small monthly or annual fee. That is the point: it can sit open as a safety net and only costs real money when you draw. Ask for the fee schedule in writing before opening one.
Lenders size limits against monthly revenue, commonly 10-20% of annual revenue for online lines. A business depositing $50K a month might see limits in the $25K-$100K band, with bank lines running larger for strong files.
Online lines are often approved and drawable in 1-3 business days, and once open, draws typically land in your account within one business day. Bank lines take 1-4 weeks to open but behave the same once active.
Fast access. Reusable funds. Built around your business.