Landscaping Equipment Financing: Costs & Terms
*A landscaping company owner looks over his yard after a new compact track loader arrives on the trailer.*
The short answer
Landscaping equipment financing is a business loan or lease for one machine: a mower, a skid steer, a track loader, a mini excavator. The machine secures the deal. That collateral is why it prices better than unsecured borrowing. Underwriters read the dealer quote as closely as your bank statements.
Commera's published equipment ranges run 12 to 84 months with 0% to 20% down. Those are illustrative, not an offer, and every deal is subject to underwriting. Factory programs run up to 60 months, per Kubota's 2026 offer.
Commera is a broker, not a lender. We compare offers from our lender partners. We arrange equipment financing through our funding partners.
Need payroll or a seasonal cash gap covered, not a machine? Start with landscaping business loans instead.
What landscaping equipment you can finance
Almost any titled or serialized machine a crew uses to earn money. Landscaping equipment financing starts with mowing iron: commercial zero-turns and stand-on mowers. Trucks and dump trailers count too. They are underwritten as business equipment when the company owns them, not the owner.
Earth-moving is where tickets get large. Skid steers and compact track loaders handle grading, hardscape and material moving. Mini excavators handle drainage, irrigation and tree work.
Attachments usually ride on the same contract as the base machine. Put them on the quote.
Then the machines that keep a crew billable between jobs: stump grinders and aerators. Snow plows and salt spreaders turn a dead quarter into winter revenue.
Makers publish no price for trucks, trailers and stand-on mowers, so the dealer quote is the only number.
What landscaping equipment costs in 2026
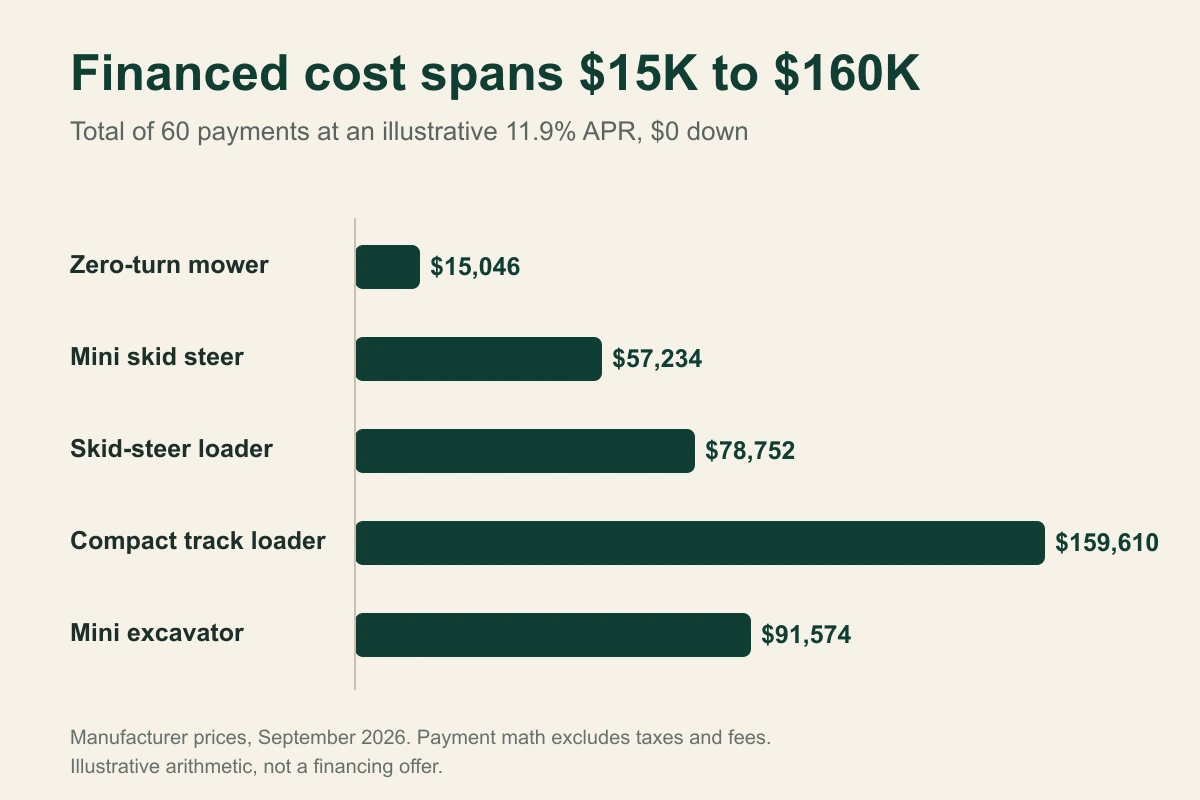
*Financed over 60 months at Commera's illustrative 11.9% APR, the same money buys a mower or a mini excavator many times over.*
Manufacturer figures as of September 2026. These are MSRP or listed price, not a dealer invoice. The zero-turn row uses the $11,299 promo price.
The payment and total columns are arithmetic, not a quote. They apply Commera's illustrative 11.9% APR to the price in that row over 60 months, nothing down, taxes and fees excluded.
| Machine and model | Manufacturer price | Illustrative payment, 60 mo at 11.9% | Total of 60 payments |
|---|---|---|---|
| Toro Z Master 2000 zero-turn, 60" | $11,299 promo / $11,799 | $250.77 | $15,046 |
| Toro Dingo TX 1000 TURBO mini skid steer | $42,980 | $953.90 | $57,234 |
| Kubota SSV75 skid-steer loader | as low as $59,139 | $1,312.53 | $78,752 |
| Kubota SVL110-3 compact track loader | as low as $119,860 | $2,660.17 | $159,610 |
| Kubota KX040-5 mini excavator | as low as $68,768 | $1,526.23 | $91,574 |
The contract amount is the dealer's out-the-door price plus attachments, freight, setup, taxes and any warranty you roll in. Get that quote first.
How landscaping equipment financing works
The machine is the collateral. The lender funds the dealer against an invoice, takes a security interest and files a UCC-1. The lien is public record.
The lender's remedy is the machine, so terms are set against useful life. Not against how long you want to stretch the payment.
That's why a skid steer loan over 60 months on a new machine is ordinary. The same term on a high-hour used unit usually isn't. Liens and lease structures are covered in our equipment financing page.
Worked example: skid steer financing over 60 months
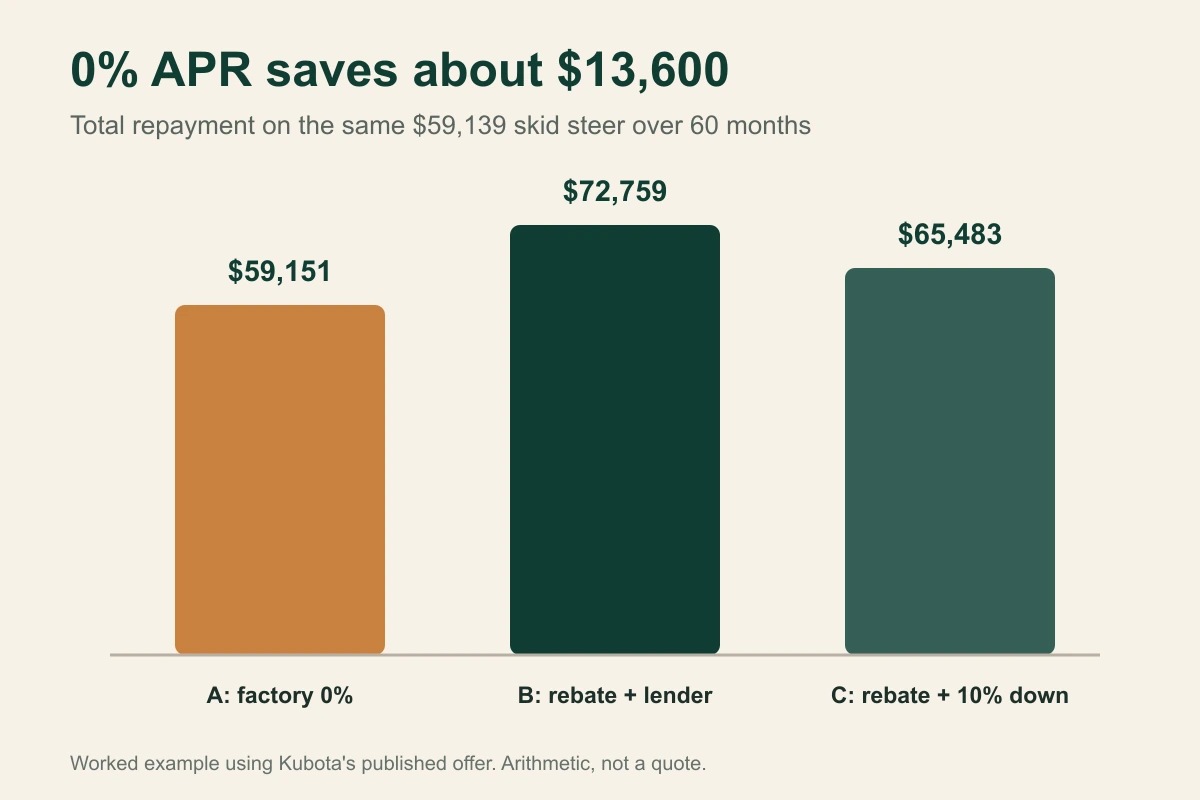
*On the same $59,139 skid steer, the factory 0% route costs about $13,600 less over 60 months than taking the rebate and financing the rest.*
Take the $59,139 SSV75 MSRP from the table above, bought new from a participating dealer over 60 months. The factory offer, as of September 2026 per Kubota, is 0% A.P.R. for up to 60 months or up to $4,500 off, not both. Three ways to buy the same machine:
A. Factory 0% A.P.R., $0 down, no rebate. Per Kubota, the factory example is 60 payments of $16.67 per $1,000 financed: 59.139 × $16.67 = $985.85 a month. The resulting $59,151 total is $12 above MSRP because Kubota's published payment factor is rounded to the nearest cent, not because this model assumes a hidden fee.
B. Take the $4,500 rebate and finance $54,639 with an independent lender at an illustrative 11.9% APR. It is Commera's calculator default, not a quote.
C. Take the $4,500 rebate and put 10% down. The down payment is $5,463.90, 10% of the $54,639 net price. That leaves $49,175.10 financed at the same illustrative 11.9%.
| A: factory 0% | B: rebate + lender | C: rebate + 10% down | |
|---|---|---|---|
| Principal | $59,139 | $54,639 | $49,175.10 |
| APR / estimated APR | 0% | 11.9% illustrative | 11.9% illustrative |
| Monthly payment | $985.85 | $1,212.66 | $1,091.39 |
| Total repayment | $59,151 | $72,759 | $65,483 |
| Interest | effectively $0 | $18,120 | $16,308 |
| Cash out of pocket | $59,151 | $72,759 | $70,947 |
A lands about $13,600 cheaper than B, if you qualify under the factory program. C shows what a down payment buys: $1,812 less out of pocket than B, and still $11,796 above the 0% route. Run your own price, down payment, and term through the funding calculator.
Dealer and manufacturer 0% vs an independent equipment lender
Factory 0% is real money. It isn't free: you pay by giving up the cash incentive. Per Kubota's 2026 terms: "Rebates not available with 0% A.P.R. or other promotional financing."
As of September 2026, the manufacturer advertises 0% A.P.R. for up to 60 months or savings up to $4,500 on skid steers, $5,200 on track loaders and $12,000 on excavators, through 12/31/2026.
Two limits matter. Eligibility: the program is "available to qualified purchasers through Kubota Credit Corporation, U.S.A.; subject to credit approval." Inventory: it covers participating dealers' in-stock equipment only.
An independent lender wins where the factory program can't reach. That means used machines, a mixed fleet in one contract, a truck and trailer bundled with the loader, or an applicant the factory declined.
New vs used equipment financing
Used skid steer financing works like any used-machine deal. Terms get shorter and rates get higher. The collateral is worth less and harder to sell as hours climb.
Expect to provide make, model, year, hours and serial number. Add a dealer invoice, or a bill of sale on a private purchase, which draws more scrutiny. Check it against real sales. Ritchie Bros publishes 24 months of auction results, filterable by model, year and hours.
Leasing a skid steer vs financing it
The difference shows up at the end of the term. A $1 buyout lease is a purchase in installments, which the IRS may treat as a conditional sales contract. A fair market value lease keeps payments lower and leaves you a choice: return the machine, renew, or buy it at its then-current value.
Tax treatment follows the contract, not the label. The IRS separates a true lease, where payments deduct as rent, from a conditional sales contract, where you recover the cost through depreciation. Have your accountant read it first.
Lawn equipment financing with bad credit: what is realistic
Weak credit doesn't disqualify you. It changes the price and shape of the deal. Every commercial equipment lender checks credit. Ads implying otherwise are describing consumer point-of-sale products.
What moves a marginal file: a larger down payment, a shorter term, equipment you own pledged as extra collateral, a co-signer.
NerdWallet reports Balboa Capital equipment-financing minimums of one year in business, $100,000 in annual revenue, and a FICO score of 620. Meeting those thresholds does not make approval automatic. ELFA's June 2026 index put the industry credit approval rate at 79.5%, and 80.7% in small-ticket. Those are approvals among applications submitted, not odds for any one file.
Cost is where owners get surprised. According to the Fed's 2026 Report on Employer Firms, 60% of borrowers who used online lenders said the actual cost ran higher than expected.
Before swapping an equipment contract for a revenue-based advance, price both. Factor-rate pricing does not represent APR. Our MCA vs equipment financing comparison shows which fits.
Lawn equipment financing vs consumer mower financing
Search "lawn equipment financing" and you'll mostly get consumer offers. That is retail point-of-sale credit, underwritten to your personal credit. Fine for a homeowner. A poor fit for a landscaping company.
A business contract is written to the entity, usually with an owner's personal repayment obligation, and keeps the asset on the company's books. That puts depreciation and expensing decisions in the business. A consumer plan parks the debt on your personal file, next to your mortgage and cards.
The exception is scale. On one mower Toro lists at $11,299 as of September 2026, consumer terms with strong personal credit can be cheaper. Once the machine works every week, write it as a business contract.
SBA and bank routes when the ticket is bigger
SBA programs price lower and move slower. A 7(a) loan runs to $5 million, and equipment is an eligible use. Maturity is ten years or less, "unless it finances or refinances real estate or equipment with a useful life exceeding ten years."
SBA rates are capped at a base rate plus a spread. Using the Federal Reserve's 6.75% bank prime rate and the SBA's maximum spreads produces an estimated 9.75% ceiling for larger loans and 12.75% for certain smaller loans.
The SBA 504 program goes to $5.5 million, built for "long-term machinery and equipment with a useful remaining life of a minimum of 10 years," with 10-, 20- and 25-year terms. Timelines vary by lender and program.
| Factory program | Independent lender | SBA 7(a) or 504 | |
|---|---|---|---|
| Typical size | One in-stock machine | Published product range | 7(a) to $5M; 504 to $5.5M |
| Term | To 60 months (2026 factory offer) | 12-84 months published | 10 yrs, longer if life >10 yrs |
| What they ask | Credit application, dealer order | Quote, bank statements, credit review | Full financials, tax returns |
| Good fit | New, single brand | Used, mixed brands, truck and trailer | Big tickets, long-life assets |
Section 179 and depreciation in 2026
For tax year 2026 the IRS Section 179 expensing limit is $2,560,000, phasing down dollar-for-dollar once qualifying purchases exceed $4,090,000, with a $32,000 cap on qualifying SUVs. Separately, 100% bonus depreciation is permanent for property acquired after January 19, 2025.
None of that makes a machine free. A deduction reduces taxable income, so the saving depends on your profit and marginal rate. Expensing the full cost now means no depreciation later.
The machine has to be placed in service in the year you claim it. Consult a tax advisor. These are 2026 IRS rules, and Commera does not give tax advice.
How to qualify and what to prepare
Underwriters weigh four things: time in business, revenue against the payment, owner credit, the asset. Have this ready:
- The written quote or invoice, with attachments, freight and setup itemized. - Recent business bank statements. - Entity details, EIN, and owner information for the repayment obligation. - For used machines, make, model, year, hours and serial number, and for larger tickets, tax returns and current financials. With those in hand, a pre-qualification takes two minutes, with no hard credit pull. Pre-qualified offers may come back within 24 hours, but timing varies.
Apply in the off-season, before the spring rush.
If the machine is new, if it's used, if the ticket is big
If the equipment is new, single-brand and you qualify with the factory credit arm then compare the 0% offer against the rebate on total cost, not monthly payment. In the illustrative example above, 0% won by roughly $13,600.
If the equipment is used, spans several brands, needs a truck and trailer in one contract, or the factory program declined you then an independent lender is the practical route.
If the ticket is large, the asset's life exceeds ten years and you can wait out a longer process then SBA 7(a) or 504 through a bank.
If what you need is working capital rather than a machine then don't finance it as equipment.
How hard is it to finance landscaping equipment?
Easier than unsecured borrowing, because the machine itself is collateral the lender can repossess. Approval still turns on time in business, revenue against the payment, owner credit and the asset. Approval rates and what moves a weak file are in the bad-credit section above.
What credit score do I need for equipment financing?
There is no single industry minimum; lenders weigh revenue and the asset alongside the score. One bank equipment lender publishes minimums, as of September 2026, of one year in business, $100,000+ in annual revenue and FICO 620 or more, while noting that meeting them "does not constitute approval."
What is the minimum credit score required to finance a skid steer?
No manufacturer or major lender publishes a hard cutoff for skid steers. Factory programs say only that the promotional rate goes to "qualified purchasers … subject to credit approval." The closest published benchmark, as of September 2026, is the FICO 620 minimum one bank equipment lender publishes.
How many years can you finance a skid steer?
Terms are matched to the machine's useful life. Commera's published equipment range runs 12 to 84 months, and factory promotional financing on new skid steers runs to 60 months at 0% A.P.R. as of September 2026. Used units get shorter terms, because hours cut what the collateral fetches.
Can I finance used landscaping equipment, and what do lenders ask for?
Yes, and it's routine. But expect a shorter term and a higher rate than on a new machine. Lenders ask for make, model, year, hours and serial number plus an invoice or bill of sale, and many cap the age or hours they finance.
Is dealer 0% financing actually cheaper than a rebate?
Often yes on a large new machine, but only if you compare total cost, not monthly payment. The illustrative worked example above runs one $59,139 skid steer three ways: factory 0%, rebate plus a lender, rebate plus 10% down. The 0% route wins by roughly $13,600, if you qualify.
Poor credit but decent revenue , what are my realistic options?
Revenue helps, but it doesn't erase a credit file: plan on a larger down payment, a shorter term, pledging equipment you own outright, or a co-signer. If you weigh a revenue-based advance instead, compare its total repayment and payment frequency against the equipment contract. Factor rates do not represent APR.
Can I get equipment financing for a brand-new landscaping business with no revenue yet?
It's difficult, because published lender minimums as of September 2026 typically start at one year in business and $100,000+ in annual revenue. The realistic paths are a factory program underwritten on your personal credit, a much larger down payment, a co-signer, or renting until you have statements to show.
If I take a personal loan for the machine, can my LLC own it?
Yes. Who owns the asset and who owes the debt are separate questions, so the LLC can hold and use the machine while you stay personally liable. Document the transfer as a capital contribution or a sale, and consult a tax advisor first.
Should I finance a mini skid steer or keep renting?
Mini skid steer financing pays off when utilization is high, so weigh the payment against a normal month of rentals. The price table above gives the illustrative 60-month payment at 11.9% APR on a $42,980 machine, arithmetic rather than a quote. If it sits on the trailer most weeks, rent.
See what your business qualifies for.
Bring the dealer quote and we'll compare offers from lender partners against it. Commera is a broker, not a lender. All financing is subject to underwriting.
Keep reading
- Landscaping Business Loans, working capital and seasonal gaps this article leaves out. - SBA Loan Guide, how 7(a) and 504 work when the ticket justifies the wait. - Factor Rate vs APR, factor-rate pricing against a contract priced in APR. ---
Sources
Toro commercial mower product pricing
Toro mini skid steer product pricing
Kubota MSRP and 2026 offers, skid steers · track loaders · excavators , https://www.kubotausa.com/special-offer/skid-steers · https://www.kubotausa.com/special-offer/track-loaders · https://www.kubotausa.com/special-offer/excavators
ELFA CapEx Finance Index, June 2026 , https://www.elfaonline.org/research/capex-finance-index/elfa-capex-finance-index-june-2026
- NerdWallet, Balboa Capital equipment financing minimums (one year in business, $100,000 annual revenue, FICO 620), https://www.nerdwallet.com/business/loans/reviews/balboa-capital Fed Small Business, 2026 Report on Employer Firms , https://www.fedsmallbusiness.org/reports/survey/2026/2026-report-on-employer-firms
Ritchie Bros auction results and equipment values , https://www.rbauction.com/equipment-values-auction-results
SBA 7(a) loans , https://www.sba.gov/funding-programs/loans/7a-loans
SBA 7(a) terms, conditions and eligibility , https://www.sba.gov/partners/lenders/7a-loan-program/terms-conditions-eligibility
SBA 504 loans , https://www.sba.gov/funding-programs/loans/504-loans
Federal Reserve selected interest rates
IRS Section 179 limits for tax year 2026
IRS, tax inflation adjustments for tax year 2026 (general context) , https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill
IRS, bonus depreciation guidance , https://www.irs.gov/newsroom/treasury-irs-issue-guidance-on-the-additional-first-year-depreciation-deduction-amended-as-part-of-the-one-big-beautiful-bill
IRS, lease vs conditional sales contract , https://www.irs.gov/faqs/small-business-self-employed-other-business/income-expenses/income-expenses-7
IRS guide to depreciating property
---